Tell us where to start
Choose car insurance and your province. Share the general reason for your enquiry, such as a renewal or a new vehicle.
Your renewal deserves a second look. Explore car insurance quotes with the coverage, deductibles and annual cost in view. Start your enquiry and find out which options fit your drivers, vehicle and budget.
 A.M. Fredericks UnderwritingABEX o/b Affiliated Broker Exchange
 Allianz Global RisksAmbri AssuranceApril Canada Inc.April MarineArthur J. Gallagher & Co
 AVRO Insurance ManagersBeazley Canada LimitedBerkley Insurance CompanyBlueCross BlueShield
 Burns & Wilcox CanadaCAA InsuranceCAN - Continental Insurance
 Cansure Underwriting LtdCaradoc Townsend MutualChes Special Risk Inc.Chubb InsuranceChutter Underwriting Services
 Core Underwriting ServicesDefinityDesjardins Financial Security Investments Inc.
 Dominion of Canada/Travelers/Travelers EssentialEagle Underwriting Group Inc.Echelon
 Excess Underwriting Corp.Facility Association
 Forward InsuranceGlobal Aerospace Underwriting
 Great-West LifeGroupAssureGroupOne Insurance
 HDI Global Specialty SE
 IA Excellence Life Insurance
 INGLE International
 Intact Public Entities
 La CapitaleLiberty International CanadaLynx Insurance UnderwritersMarkel
 NorthbridgeOld Republic
 Optiom
 PAL Insurance Brokers Canada
 Premier Canada AssurancePremier MarinePremium Marine
 Revolution Advanced Underwriting
 SignalSignature Risks
 South Western GroupSovereign GeneralSpecial Risk InsuranceSports & Fitness InsuranceSSQ AssuranceStarr Technical RisksStrategic UnderwritingSummit Underwriting Group Inc.The Boiler Inspection and Indemnity Company (BI&I)
 The Totten Insurance GroupTrans Canada
 TravelersTrinity Underwriting
 Unique Risks
 Victor Insurance
From Insurance Genie
Explore recent policy purchases shared through our participating insurance professionals.
Recent policies will appear here when the Insurance Genie CRM feed is connected.
Whether you are renewing, buying a car or adding a driver, a useful comparison starts with the right information.
Choose car insurance and your province. Share the general reason for your enquiry, such as a renewal or a new vehicle.
Have your current policy, drivers, vehicle and driving routine ready for the participating licensed provider.
Review actual offers, ask about differences and confirm the terms and start date before relying on new coverage.
For Ontario enquiries, learn about our brokerage partner Billyard Insurance Group Vaughan. Availability depends on the product, province and provider.
Car insurance · comparison examples
Explore three car insurance illustrations, then compare your own coverage. These assumed amounts show the maths, not available rates or recent customer quotes.
Examples rotate as you browse
Assumed amounts · CAD per year
Keep vehicle, driver, use and coverage details consistent when requesting proposals. Illustrative amounts, not a quote.
Compare liability limits, accident benefits, deductibles and optional coverages alongside price. Illustrative amounts, not a quote.
A different deductible changes your share of a covered loss. Ask for actual options and compare the tradeoff. Illustrative amounts, not a quote.
Illustrations use assumed premiums and are not insurer offers, customer results or guaranteed savings. Compare the same limits, deductibles and coverage before choosing. .
Insurance Genie is an insurance request platform, not an insurer or insurance brokerage. Requests may be connected with participating licensed partners. Availability depends on your location, needs and partner eligibility. A request is not a quote or confirmation of coverage.
When looking for cheap car insurance in Ontario, check the annual premium and the coverage behind it. Monthly payment amounts can be difficult to compare when payment fees, deposits or policy terms differ.
Ask the licensed professional to explain required and optional coverage and any change from your current policy. Include every regular driver, your actual address, vehicle use and annual distance.
Compare the same drivers, vehicle use, limits and deductibles, then check the full annual cost. A cheaper car insurance quote can reflect a different level of protection or a higher amount you pay after a claim.
| Coverage or cost | What to check | A useful question |
|---|---|---|
| Third-party liability | The selected limit for covered injury or property-damage claims against you. | Does this limit fit my circumstances and any vehicle agreement? |
| Accident benefits | Mandatory benefits, optional selections and limits for eligible accident-related injuries. | Which benefits are included, and how do they work with my other benefits? |
| Uninsured automobile | The policy's conditions for injury or eligible vehicle-damage claims involving an uninsured or unidentified driver. | When does this section respond? |
| Direct compensation – property damage | Applicable Ontario accident conditions and whether you have elected not to claim this coverage. | What would I give up by opting out? |
| Collision and comprehensive | Optional protection for vehicle damage, covered causes and separate deductibles. | What is covered for a collision, theft or other damage? |
| Annual price and payment terms | The quoted policy term, total premium, instalment costs and initial payment. | What is the full cost for the same period and coverage? |
Ontario coverage background: FSRA's standard auto policy guide and coverage and deductible choices. Other provinces have different requirements; use the rules and wording for your location.
Your driver and vehicle information, location, use and chosen coverage can affect the proposal. An online average is not a quotation for your household.
Ask about eligible discounts without assuming they are automatic. If comparing home and auto together, review the separate coverage and deductibles for each policy.
There is no single cheapest insurer for every driver. Compare suitable offers before renewal and ask which discounts you qualify for.
Prices and your needs can change. Give yourself time to review another offer against the policy you already have.
Some insurers offer multi-policy or multi-vehicle discounts. Compare the combined cost with keeping policies separate.
Explore home insurance →Update changes to commuting, annual distance and how the vehicle is used. Ask whether a change affects your quote.
A higher deductible may lower the premium. Weigh that against what you could pay after an insured loss.
Compare two annual amounts →Based on FSRA's guidance on saving on auto insurance. Discount eligibility and amounts vary.
A complete, consistent set of details helps the provider compare the right risk. Gather these before your conversation.
Share sensitive documents only through the receiving provider's appropriate secure process. The initial Insurance Genie enquiry does not require payment details, licence numbers or uploaded policy documents.
Insurers assess risk using their own approved pricing approach and claims experience. Your vehicle, driving history, location, annual distance and coverage selections also matter. Give each provider the same information before comparing the resulting annual premiums. FSRA explains rate factors.
Use your actual parking address and driving routine, including who drives the car and any commute or business use. Compare the same coverage, deductibles and policy dates. A city average is a starting point for research, not a premium you can purchase. Explore our local car insurance guides for your area.
Start with the full cost for the same policy period. Then check the payment schedule, initial payment and any instalment charges. Dividing an annual premium by twelve is a budgeting calculation; it does not confirm the insurer's monthly payment offer.
Start before the renewal deadline so you have time to gather documents, ask questions and review proposals. The provider can explain quote validity, cancellation terms and the effective date. Confirm replacement coverage before cancelling the current policy. Read FSRA's shopping guidance.
No. The cards on this site are labelled calculations using assumed amounts. An actual car insurance quote requires the provider to assess your own details. Use the cards to understand the arithmetic, then start an enquiry for the next step.
Reviewed September 10, 2026 against the linked FSRA consumer guidance. General comparison information; the licensed provider confirms your policy terms.
Your questions, answered
Affordable car insurance starts with accurate information and equivalent coverages. Use the insurer’s actual offers to decide whether a lower annual cost represents a suitable saving.
Compare the same drivers, vehicle, use, limits and deductibles. Ask about eligible discounts and payment costs, then review what is covered. Cheap auto insurance Ontario offers should not be judged by a monthly headline alone.
Yes. Ask for equivalent coverage and a clear explanation of optional choices. Compare auto insurance Ontario proposals using the annual premium, fees and deductibles, and decide what you could afford to pay after a loss.
Prepare the overnight address, vehicle details, drivers, annual distance, claims and current policy. Explain commuting, delivery, rideshare or business use accurately before comparing the results.
No. There is no one cheapest auto insurance Ontario provider for everyone. The available premium depends on the application and insurer. Insurance Genie does not guarantee the lowest rate or a fixed percentage saving.
Ask which available policies match your drivers, vehicle and coverage needs. Review limits, deductibles, exclusions, payment terms and claims service. A best or cheapest label is not evidence that the offer is appropriate for your particular circumstances.
Ask whether a participating provider has a suitable home and auto option and whether you qualify. Compare the combined annual cost with separate policies while keeping coverage assumptions consistent. A bundle is an option to assess, not a guaranteed discount.
The current website provides an enquiry route and comparison guidance; it does not issue an instant insurer-approved premium. A participating licensed provider must assess the details and confirm the offer. An enquiry does not activate insurance.
Disclose the actual licence history, training, primary driver and vehicle use. Ask which options can consider the driver and which conditions apply. Do not name someone else as the main driver simply to obtain a lower estimate.
No. Use an honest annual estimate and explain the actual routine. Ask about any available low-distance or usage-based option and its conditions, then update the provider when the way the vehicle is used changes.
No. Quotes and prices depend on individual information, underwriting and participating partner availability. Compare equivalent coverage and confirm the final terms with the licensed organization.
You can start an insurance request and prepare the information a licensed provider needs. Availability depends on participating licensed partners and your insurance needs. Explore the car insurance location guides.
This page is general information. Ask the licensed professional handling your request to explain the proposed wording, limits, deductibles and exclusions. Coverage must be confirmed by the organization arranging it.
Background reading: Provincial auto insurance information. Content updated September 9, 2026; coverage and availability remain subject to confirmation.
Contact us to discuss provider availability and the details needed for a useful conversation.
Explore my optionsClear answers to help you compare coverage and prepare for a licensed insurance review.
To find low cost auto insurance, compare the same drivers, vehicle, use, limits and deductibles. The lowest car insurance rates in Ontario vary by applicant and insurer; “best deals on auto insurance” and “great car insurance deals” are useful only when the coverage and conditions also fit. Cheap online car insurance should still be checked against the full annual cost. Start a quote review, ask what is included, and obtain the insurer's confirmation before treating a request to buy car insurance online as completed coverage.
Cheap car insurance in your area depends on your own address and circumstances. Provide the actual overnight parking location and commute, including where you keep the vehicle when you are away from home. Compare coverage before selecting the cheapest quote, and describe moves or changes of use accurately. Nearby rates are not substitutes for your personal quote, and this guide does not claim a local office in every community.
Ask a licensed provider whether a short term car insurance quote is available for your actual reason, dates, vehicle and province. Do not assume one day car insurance, weekend only car insurance or one month car insurance works like an annual policy paid monthly. Availability and minimum premiums vary. When comparing short term car insurance companies, check the exact coverages, effective dates, cancellation charges and any restrictions. A cheap advertised daily price is not confirmation that an insurer can cover your situation.
The cheapest car to insure in Ontario depends on the model, year, driver and coverage. Request quotes for each vehicle before making a purchase. For Kia Soul car insurance, Kia Rio car insurance or Kia Optima insurance, give the exact year, trim and use; a model-name average cannot establish your insurance cost. For a Bentley or another higher-value vehicle, ask about repair arrangements, valuation and any specialist insurer requirements. The car's purchase price alone does not establish the premium.
A car insurance calculator can illustrate a budget or compare prices you enter; a real insurer quote requires your individual information and underwriting review. A regional estimate does not replace a personalized insurer quote. Our savings comparison uses your figures and does not generate insurance prices. To obtain an actual quote, use the insurance enquiry options.
A tight budget is a reason to compare eligible discounts, total payment costs and an affordable deductible. It is not a guarantee of a no-down-payment policy or a premium below $100 a month. Ask for the initial payment, remaining instalments and fees in writing. Ontario rules prohibit using income and credit history in auto risk classification; other provinces differ. FSRA discusses prohibited rating factors. Accurate driving, vehicle and claims information still matters.
Tell the licensed provider about the actual drivers, licence status and any vehicle adaptations needed. Ontario prohibits denial of auto insurance solely on specified grounds including disability or being newly licensed; eligibility still depends on the applicable rules. A suspended or absent licence requires a specific discussion and never authorizes driving. A non-owner, stored vehicle or learner-driver situation should not be treated as an ordinary active-driver quote. Read FSRA's consumer guidance.
No label identifies the cheapest insurer for everyone. A teenager, first-time driver, newcomer, mature driver or retiree should compare quotes for the actual licence history, vehicle and use. Ask about qualifying student, training, retiree or group discounts without assuming all women, men, teachers, professionals or veterans receive one fixed price. For someone over 50, 65 or 80, review the same coverage and deductible questions. Do not remove needed protection solely to match an advertised example.
Full coverage is a marketing expression, not a promise that every loss is covered. Ask the provider to list required protection, collision, comprehensive and any optional benefits or endorsements included in the quote. A third-party liability limit is only one part of that review. Compare deductibles, sometimes called excesses elsewhere, and exclusions too. For motorcycles, leisure vehicles, rental cars or company vehicles, ask which policy or endorsement fits that particular use rather than assuming personal car coverage applies.
Availability depends on the licensed provider, required information and insurer acceptance. An online enquiry can be sent at any time, but it does not guarantee same-day placement or a person available immediately. Use the contact details shown on this site to confirm hours and the right team. For an existing claim, use the insurer and policy contact information on your own documents. Do not assume a general enquiry number is a universal insurer claims line.
Ask for a quote using the exact year, model, trim, ownership and use. GMC, Genesis, Jeep or Dodge vehicles cannot be priced from the badge alone; the same is true for any used car. When adding another vehicle, disclose every driver and ask whether a multi-vehicle option is available. Compare the total annual cost of both arrangements. The cheapest vehicle or city in a published list cannot establish your own premium.
There is no city price that applies to every driver. Insurers assess the actual address alongside the vehicle, drivers and use. A comparison of average rates by city should not be used to replace your real address with a cheaper one. Request a personal quote for where the vehicle is kept. Our city guides explain comparison questions; they do not promise a local office, a real-time ranking or one universal lowest rate.
Find city and town preparation guides across the provinces. Use your actual location and confirm the provider’s provincial availability.
Explore city and town guides →Be prepared
Hypothetical situations to help you prepare questions—not actual client claims or promises of coverage.
Scenario: A driver damages their vehicle in a collision.
What happens next: Record the incident and ask how fault, selected collision protection and the deductible affect the assessment.
Scenario: A parked vehicle is stolen.
What happens next: Report the theft and provide the requested records. The insurer will check theft protection, exclusions and settlement terms.
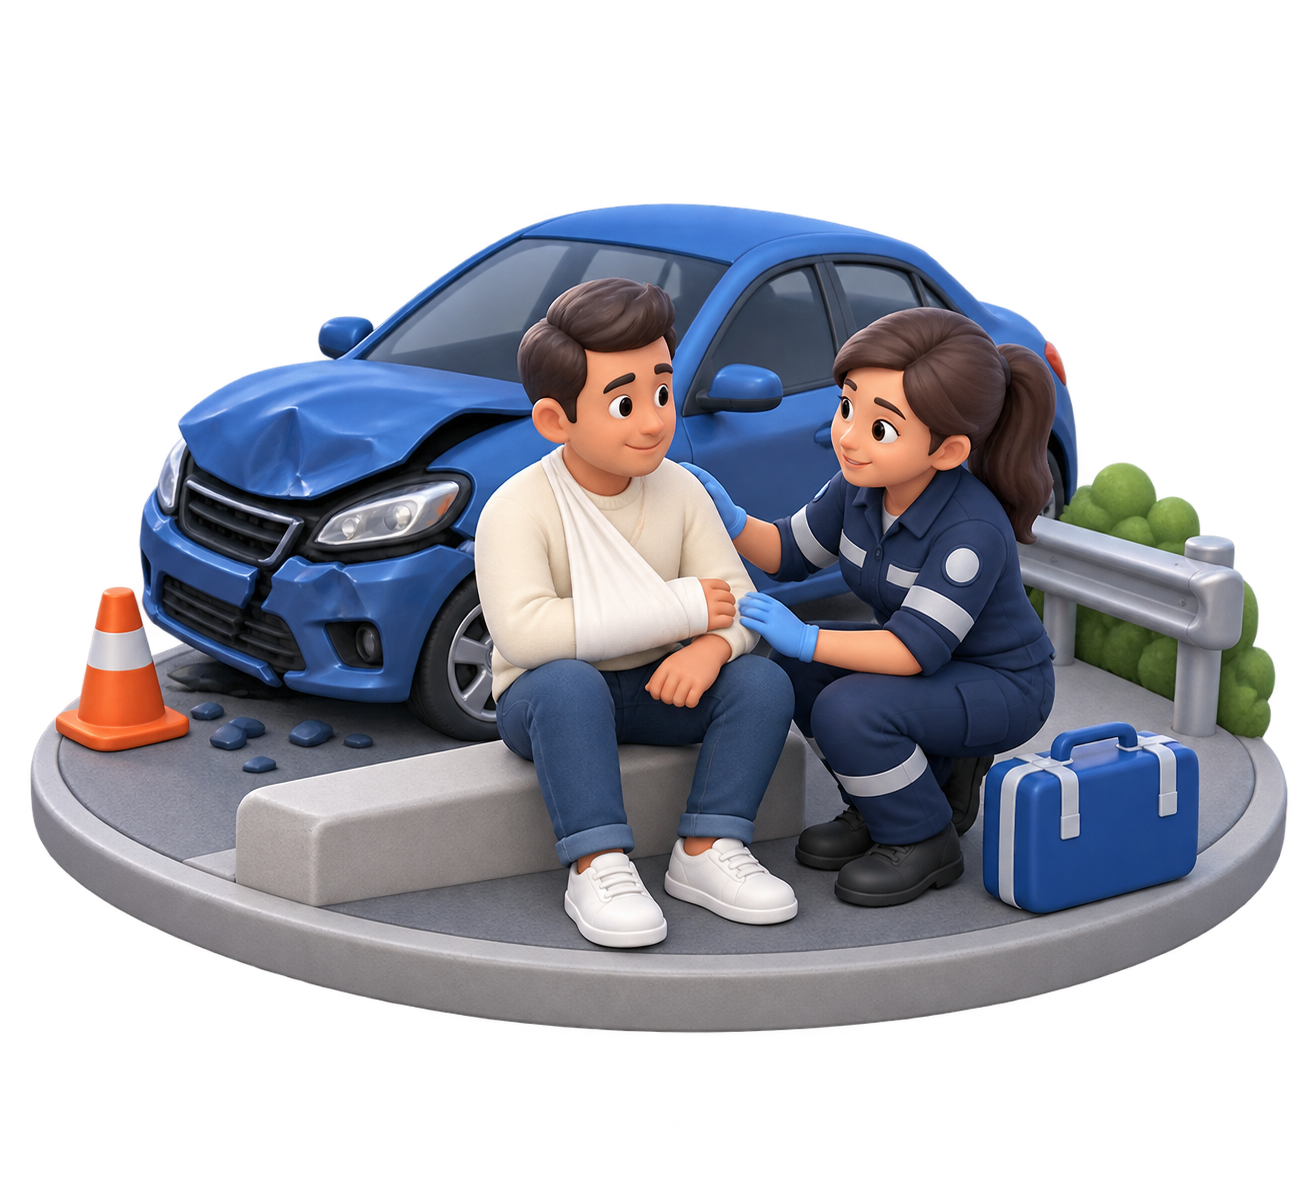
Scenario: Someone reports an injury following a road accident.
What happens next: Seek necessary care and notify the insurer. Applicable provincial benefits, liability rules and policy terms determine the next steps.
Actual outcomes depend on the facts and applicable wording. Read claims guidance · Ask about the next step
Choose your city or town to prepare a local comparison.
Hi, I’m Genie. I can explain how this website works, help you find a page, or point you to a person. I can’t answer coverage questions or give insurance advice.