Tell the home’s story
Have the address, ownership, occupancy and recent updates ready. Mention rental use or a home business.
Skip to content
Buying, renewing or moving? Explore home insurance in Ontario for your house, condo or rental. Compare protection, price and potential savings with your property in mind.
 A.M. Fredericks UnderwritingABEX o/b Affiliated Broker Exchange
 Allianz Global RisksAmbri AssuranceApril Canada Inc.April MarineArthur J. Gallagher & Co
 AVRO Insurance ManagersBeazley Canada LimitedBerkley Insurance CompanyBlueCross BlueShield
 Burns & Wilcox CanadaCAA InsuranceCAN - Continental Insurance
 Cansure Underwriting LtdCaradoc Townsend MutualChes Special Risk Inc.Chubb InsuranceChutter Underwriting Services
 Core Underwriting ServicesDefinityDesjardins Financial Security Investments Inc.
 Dominion of Canada/Travelers/Travelers EssentialEagle Underwriting Group Inc.Echelon
 Excess Underwriting Corp.Facility Association
 Forward InsuranceGlobal Aerospace Underwriting
 Great-West LifeGroupAssureGroupOne Insurance
 HDI Global Specialty SE
 IA Excellence Life Insurance
 INGLE International
 Intact Public Entities
 La CapitaleLiberty International CanadaLynx Insurance UnderwritersMarkel
 NorthbridgeOld Republic
 Optiom
 PAL Insurance Brokers Canada
 Premier Canada AssurancePremier MarinePremium Marine
 Revolution Advanced Underwriting
 SignalSignature Risks
 South Western GroupSovereign GeneralSpecial Risk InsuranceSports & Fitness InsuranceSSQ AssuranceStarr Technical RisksStrategic UnderwritingSummit Underwriting Group Inc.The Boiler Inspection and Indemnity Company (BI&I)
 The Totten Insurance GroupTrans Canada
 TravelersTrinity Underwriting
 Unique Risks
 Victor Insurance
From Insurance Genie
Explore recent policy purchases shared through our participating insurance professionals.
Recent policies will appear here when the Insurance Genie CRM feed is connected.
A few useful details can turn a broad search into a focused conversation about your home.
Have the address, ownership, occupancy and recent updates ready. Mention rental use or a home business.
A renewal notice or policy summary helps you compare limits, deductibles and the total annual cost.
Review water protection, valuables and possible home-and-auto savings with the receiving provider.
Insurance Genie provides information and referral support. Provider availability and property eligibility are confirmed when you enquire.
Meet our partners →Use your renewal date and current policy as a starting point. Note changes to the home, occupants or use, and ask what information a provider needs to compare options. You can begin with the contact options even if you are still gathering details.
Put the total annual cost next to the same requested coverage and deductibles. Ask which terms changed and whether fees apply. A useful comparison explains both the price difference and what you would be responsible for after a claim.
Home insurance · comparison examples
Explore three home insurance illustrations, then compare your own coverage. These assumed amounts show the maths, not available rates or recent customer quotes.
Examples rotate as you browse
Assumed amounts · CAD per year
Ask about unit improvements, personal property, loss assessment and deductibles. Illustrative amounts, not a quote.
Check rebuilding limits, water coverage, exclusions and deductibles before comparing home proposals. Illustrative amounts, not a quote.
A lower price can include different water limits or exclusions. Compare the same coverage questions. Illustrative amounts, not a quote.
Illustrations use assumed premiums and are not insurer offers, customer results or guaranteed savings. Compare the same limits, deductibles and coverage before choosing. .
Insurance Genie is an insurance request platform, not an insurer or insurance brokerage. Requests may be connected with participating licensed partners. Availability depends on your location, needs and partner eligibility. A request is not a quote or confirmation of coverage.
Your home is more than its purchase price. Use our home insurance guide to prepare questions about your building, belongings and the coverage you want to compare.
Explore home coverage →For a house, describe the building and contents accurately. A condominium unit owner should compare their responsibilities with the condominium corporation’s insurance. A tenant should discuss their own belongings and liability rather than relying on a landlord’s policy.
If you rent the home to others, offer short-term stays or operate a business from it, disclose those activities. They can change the type of insurance that should be considered.
Have the address, property type, approximate construction date, occupancy, updates to major systems and claims history ready. Include existing policy details and your preferred effective date.
Tell the licensed professional about renovations, vacant periods, tenants, business activities and short-term guests. Ask for the effect of any proposed deductible or coverage change to be explained.
A province-wide price does not tell you the cost for your property. The insurer needs details of the home and proposed coverage to assess a request.
If you are exploring house insurance alongside car insurance, ask about eligible bundle options and compare both policies. Insurance Genie does not guarantee a saving or that every partner offers every product.
Landlord insurance · Short-term rental insurance · Home-based business insurance · Car insurance
Your questions, answered
Home insurance, house insurance and homeowners insurance are common ways to describe protection for a home. The right comparison depends on whether you own, rent or own a condominium.
Discuss the building, belongings, personal liability, additional living expenses and the way the home is occupied.
Review the unit owner’s responsibilities alongside the corporation’s policy, including improvements and deductible questions.
Identify whose belongings and liability need protection, especially when roommates share an address.
Compare the same property details, rebuilding or contents values, deductibles and requested coverages. Home insurance quotes Ontario residents receive should be reviewed for insured events, water-related options, special limits, exclusions and living-expense conditions, not only the premium.
A homeowner, condominium unit owner and tenant have different property interests. Ontario house insurance should be matched to ownership and use. A condo insurance quote needs the corporation’s insurance responsibilities and the unit owner’s improvements, belongings and liability to be clarified.
An average cannot price a particular unit. Values, building details, coverage, deductibles and claims can differ. For a condo insurance quote, use the actual property and compare the proposed terms rather than treating an online average as your premium.
This website provides information and an enquiry route; it does not currently issue an instant insurer-approved online home insurance quote. Ask a participating licensed provider about the next step and what information is needed to assess the property.
Use the same rebuilding or contents assumptions and the same requested cover. Ask about eligible discounts and a combined home and auto review, then compare the annual cost, fees and deductibles. A lower price does not show a like-for-like saving if important cover has been removed.
Prepare construction and renovation details, roof and major systems information, occupancy, prior claims, security and a realistic contents estimate. Explain a home business, rental use, valuable items or an extended absence before relying on a proposal.
No universal best policy fits every condominium owner. Review the unit, corporation’s policy, deductibles, improvements, special limits and liability. Ask the licensed provider to identify any gaps or overlap between the proposal and the corporation’s responsibilities.
A tenant enquiry should address the renter’s belongings, personal liability and any additional living-expense cover offered. Ask about roommates, valuable items, limits and exclusions. The landlord’s building policy does not replace the tenant’s own review.
Ownership, occupancy and building responsibilities matter alongside the address. Start with the right type of home enquiry before comparing prices.
When comparing home insurance, identify whether you own a house, own a condominium unit or rent the home. Prepare the building or unit details, contents values, current deductibles and any water-coverage questions. Explain a rented basement, roommates or a home business rather than assuming a standard household description is enough. Ask the provider to compare the same requested protection and total annual cost. FCAC explains home, condo and tenant insurance.
A condo insurance enquiry should begin with the unit and the condominium corporation’s insurance responsibilities. Have your contents estimate, improvements, current deductible and any corporation insurance summary available. Explain whether you live in the unit, rent it out or use it for short stays. Ask which unit-owner responsibilities and assessments the proposal addresses. For a home that is not a condominium, first confirm the ownership and occupancy rather than comparing a condo premium with a whole-house proposal. Read FCAC’s condominium guidance.
No. A homeowner and a tenant have different property interests. A tenant policy generally focuses on the tenant’s belongings and liability; the landlord’s building insurance does not replace it.
Do not assume it does. Ask which water damage events are included, which require optional coverage and what exclusions and deductibles apply.
Start an insurance request with accurate property details. A participating licensed partner may assess it, subject to location, eligibility and availability. The request itself does not confirm coverage.
Before comparing home insurance, make a practical inventory of your furniture, electronics, clothing and other belongings. Note items that may need a separate conversation, such as jewellery, collections or business equipment. Describe renovations, a finished basement, tenants and any short-term hosting. Accurate details help a licensed professional compare proposals based on the same household and property use.
Ask how each option treats rebuilding, replacing belongings and living elsewhere after an insured event. Then ask about water damage, special limits and the deductible for each relevant event. Do not assume the headline deductible or a broad policy name describes every part of the offer.
Explore home insurance savings by asking about eligible home-and-auto bundles and any recognized protective devices. Compare the total cost of both policies, including payment arrangements, rather than only the advertised discount. Share updates to the roof, plumbing and heating accurately, and ask whether they affect terms. Request deductible alternatives only after considering the amount your household could comfortably pay after a loss.
Hypothetical example: a homeowner finishes a basement and plans to rent it out. Before the first tenant arrives, they should discuss the renovation, occupancy and any landlord-owned furnishings with the insurance professional. Their earlier home description would no longer tell the full story. The scenario explains a review trigger, not a guarantee that property damage or a tenant-related claim would be covered.
This page is general information. Ask the licensed professional handling your request to explain the proposed wording, limits, deductibles and exclusions. Coverage must be confirmed by the organization arranging it.
Background reading: Consumer insurance coverage guidance. Content updated September 9, 2026; coverage and availability remain subject to confirmation.
Contact us to discuss provider availability and the details needed for a useful conversation.
Explore my optionsClear answers to help you compare coverage and prepare for a licensed insurance review.
To find house insurance quotes, prepare the address, construction details, building updates, occupancy and claims history. An online house insurance quote is only useful when the information and coverage are comparable. Compare house insurance companies in Ontario using the same rebuilding estimate, contents values, deductibles and optional water protection. The best home insurance rates in Ontario are the rates that meet your needs at an acceptable total cost; no company is lowest for every home. Review any conditions attached to house insurance deals before selecting cheap home insurance.
Home content insurance, often called contents insurance, concerns your belongings. Building insurance concerns the dwelling itself. For home insurance in Ontario, Canada, estimate the cost to replace possessions and ask how limits apply to jewellery, art, electronics and business equipment. For luxury home insurance, discuss specialist rebuilding features and valuable items rather than assuming a standard limit is enough. IBC explains buying adequate home insurance.
A condo insurance estimate depends on the unit, contents, improvements, deductible and the coverage needed alongside the condominium corporation's policy. Compare lower-cost condo insurance proposals only after matching those needs. A condo insurance calculator can help organize values, but cannot confirm an insurer's acceptance or final premium. Ask for a personal quote and review loss assessment and corporation-deductible coverage where offered. IBC explains condominium coverage.
When comparing a proposal from a direct insurer with one arranged by a broker, use the same property details, rebuilding and contents values, coverages and deductibles. Ask who provides advice, which insurer issues the policy, and who handles changes or claims. This website routes enquiries to participating licensed partners; it does not itself issue home insurance. Compare the written terms and total cost rather than assuming either route is always cheaper.
You can prepare a home insurance enquiry online, but purchase and the effective date require the licensed organization's confirmation. Homeowners insurance quotes, residential house insurance estimates and dwelling-coverage proposals should use accurate building and occupancy details. A home insurance calculator or apartment insurance estimator can help organize values; it cannot verify eligibility or produce an insurer-approved premium without an assessment. Compare written proposals rather than assuming a quote, application and issued policy are the same.
First establish ownership and occupancy. A freehold townhome usually needs a different review from a condominium townhome with a corporation policy. A condo owner should review contents, improvements, liability and possible assessments alongside that corporation's coverage. A tenant normally needs protection for their own belongings and liability rather than the building owner's whole policy. For an apartment building, group home, estate property or unusual accommodation, describe the full occupancy and use so the provider can identify the correct market.
For a mansion, estate home or other high-value property, discuss the actual rebuilding features, professional valuations where needed and valuable belongings. Do not substitute the purchase price for the rebuilding assessment. Household contents insurance should reflect an inventory and the limits that apply to particular items. Comparing house and contents insurance means reviewing both the dwelling and possessions, along with liability, deductibles and optional coverage. A higher-value description does not itself guarantee enhanced wording.
There is no single cost that applies to every condo, rented house or apartment. The quote depends on the property, occupancy, coverage, deductibles and insurer. Tell the provider if a condo is rented to tenants or used for short stays. Compare condo insurance quotes with the same assumptions and ask whether landlord protection is needed. A tenant's contents premium should not be used as a comparison for the cost of insuring the building.
Request both a combined home-and-auto proposal and suitable separate quotes using the same coverage. Auto and condo insurance may also be eligible for a multi-policy option, subject to the insurer's rules. Compare the total cost, not just the advertised discount. The household's claims, drivers, property and occupancy still need to be assessed. A discount on one policy does not mean every combined offer is the best fit.
Check the condominium corporation's moving rules and ask the mover for the evidence the building requires. Requirements can differ by property. A mover's certificate does not establish that all of your possessions are insured in transit, and your own unit policy should not be assumed to cover every moving loss. Confirm booking, elevator and insurance requirements with the building and review the mover's contract before the moving day.
Ask whether the proposed policy insures fire damage to the building and belongings, and review limits, deductibles, exclusions and additional living expenses. Home, condo and tenant arrangements differ: a tenant does not insure the landlord’s building in the same way as an owner. Describe occupancy, heating and renovations accurately. Read IBC’s explanation of home coverage types; the actual policy determines a claim.
Prepare the claim dates, causes, amounts if known, current status and repairs or prevention work completed. Answer the insurer’s questions accurately and distinguish a closed claim from an unresolved loss. A prior claim does not allow this website to predict acceptance or price. Ask the receiving provider what evidence it needs and compare any proposed deductibles, exclusions and annual cost before deciding.
Find city and town preparation guides across the provinces. Use your actual location and confirm the provider’s provincial availability.
Explore city and town guides →Be prepared
Hypothetical situations to help you prepare questions—not actual client claims or promises of coverage.
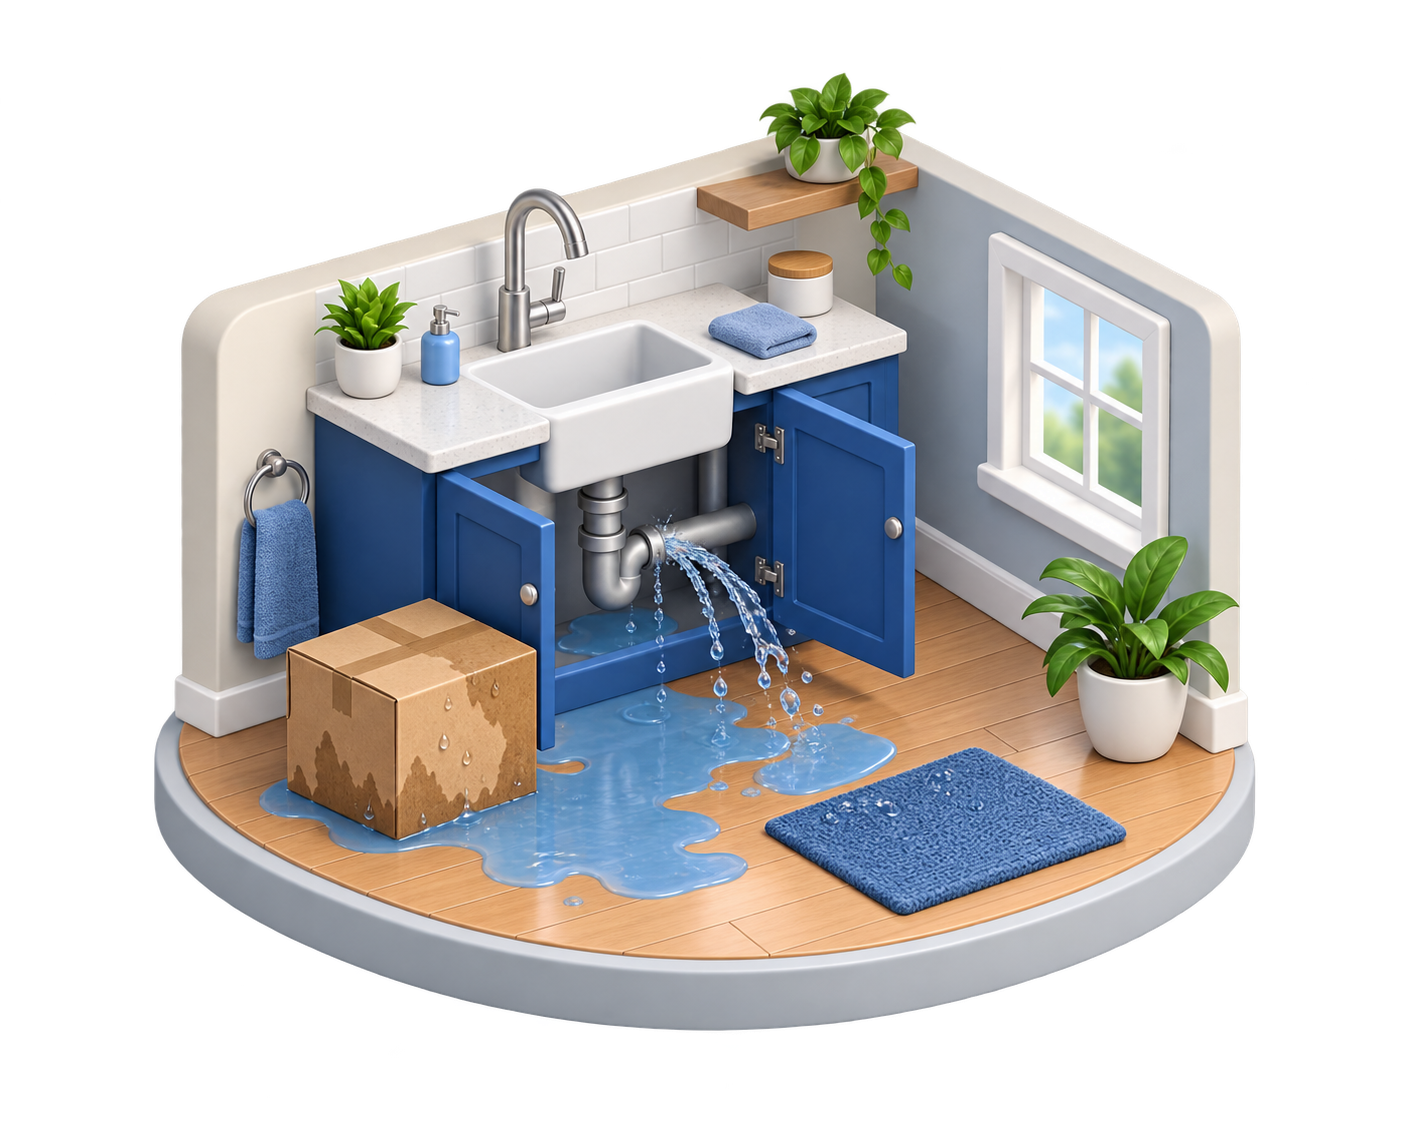
Scenario: A pipe breaks and damages flooring and belongings.
What happens next: Document the source and damage. The insurer will review the cause, policy wording, limits and deductible; different water events have different treatment.
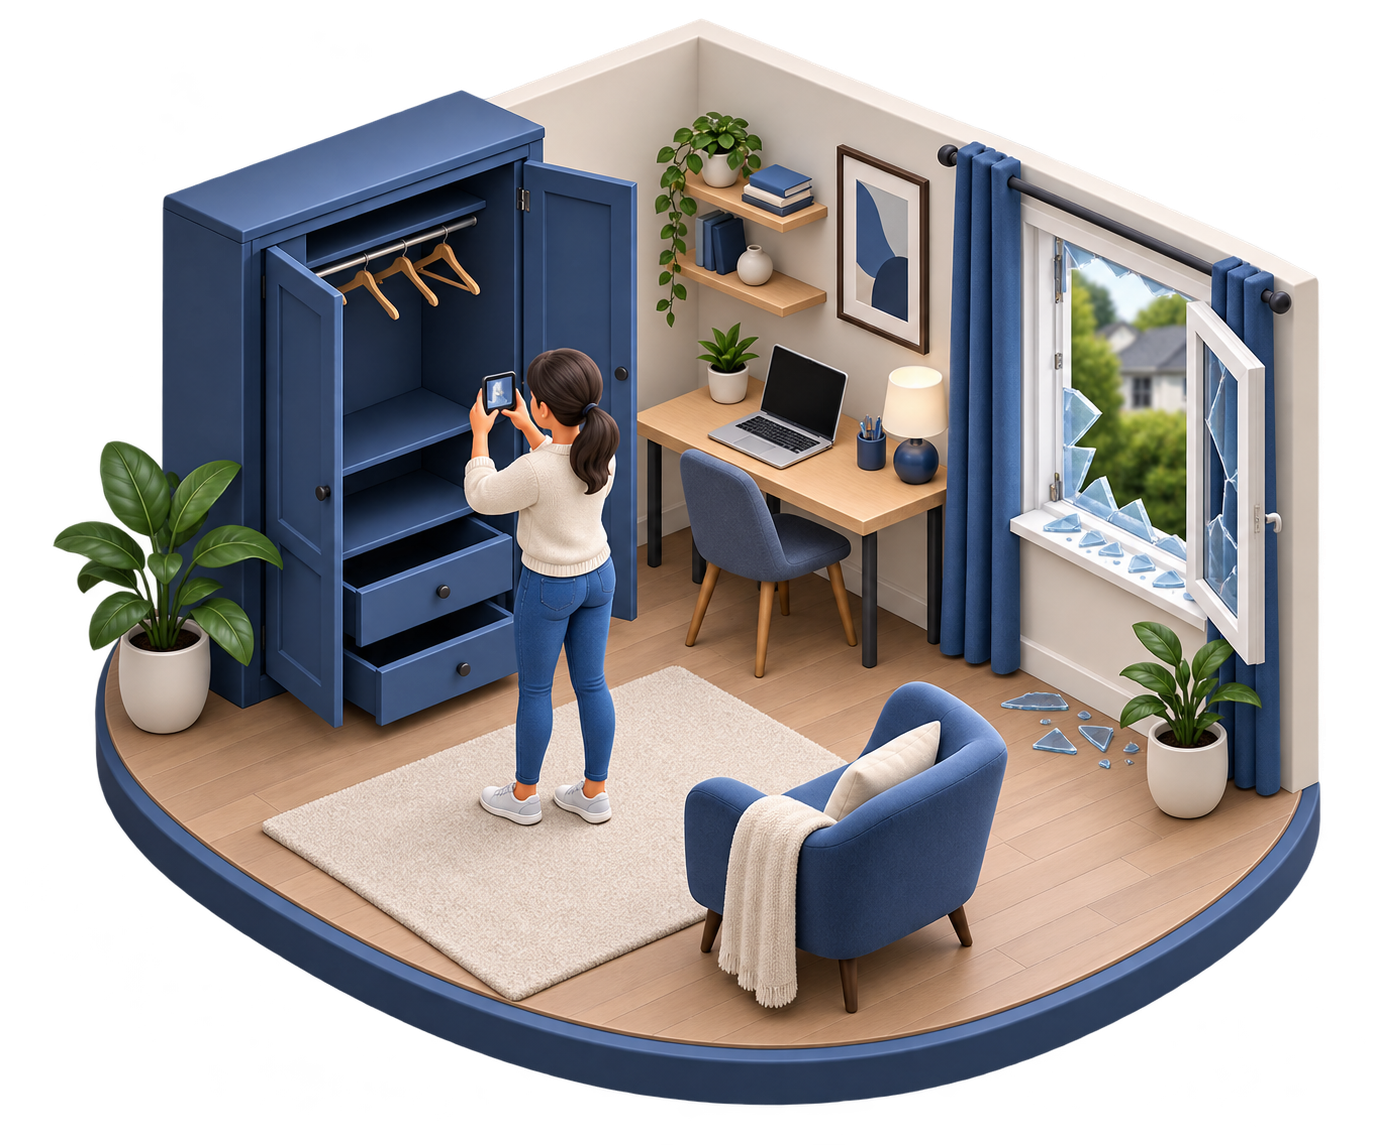
Scenario: Personal belongings are taken during a break-in.
What happens next: Keep police details and proof of ownership. Item limits, valuation and any scheduled coverage are part of the assessment.
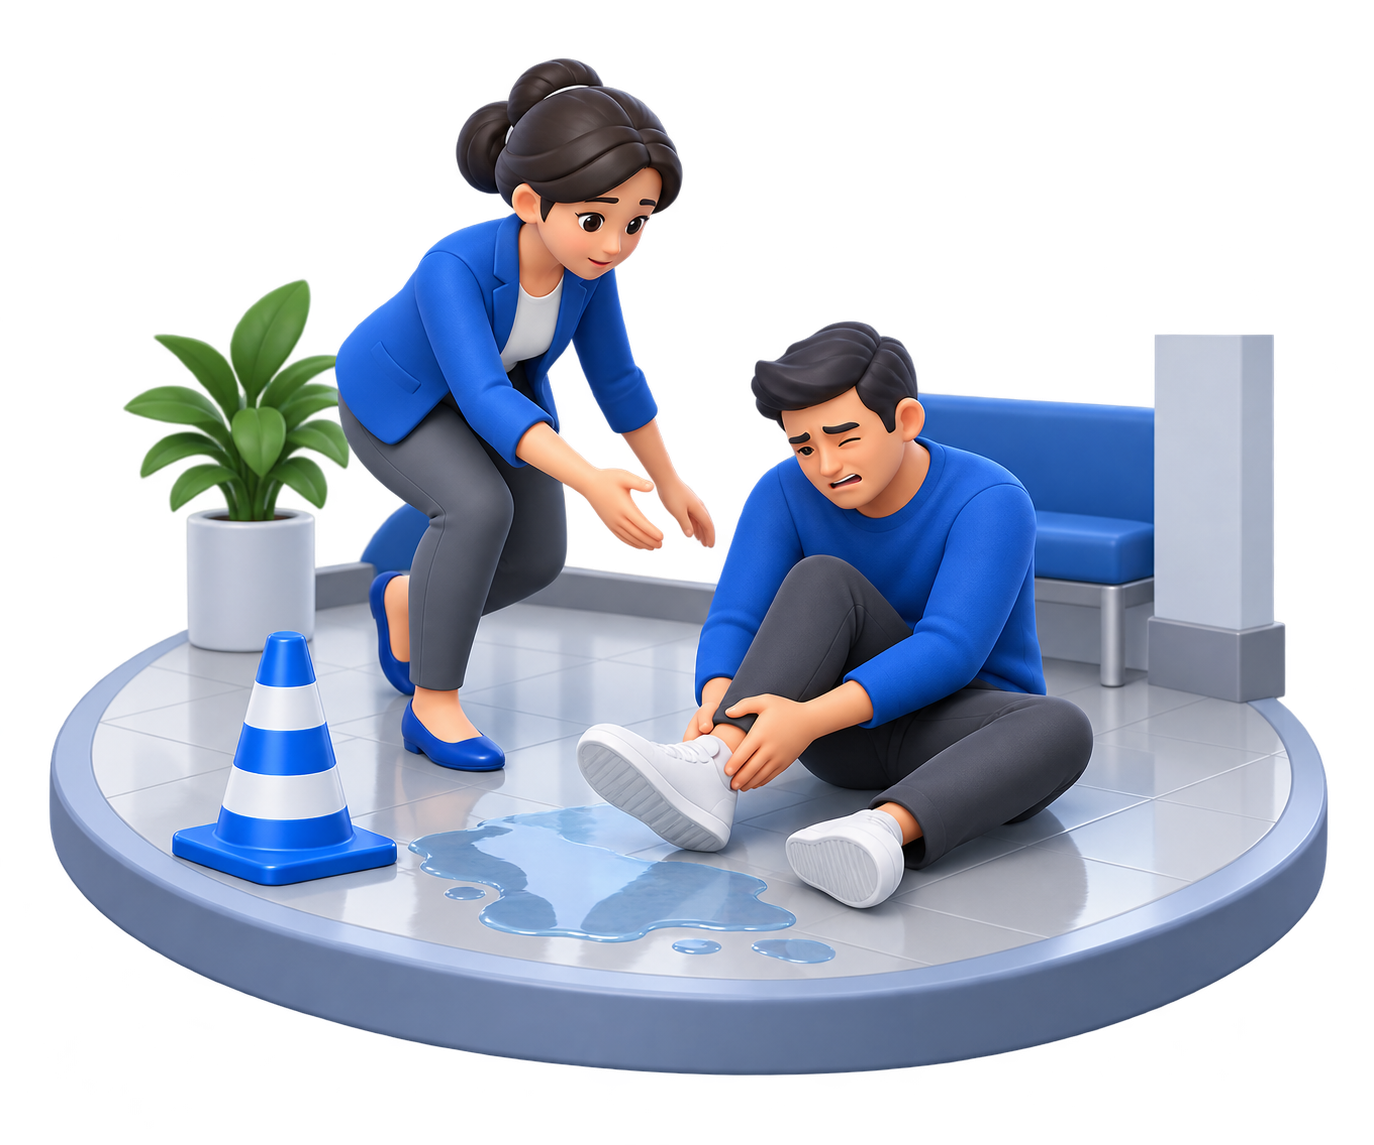
Scenario: A visitor alleges an unsafe condition caused an injury.
What happens next: Send the allegation to your insurer promptly. Liability and the policy response require investigation rather than an assumed payout.
Actual outcomes depend on the facts and applicable wording. Read claims guidance · Ask about the next step
Choose your city or town to prepare a local comparison.
Hi, I’m Genie. I can explain how this website works, help you find a page, or point you to a person. I can’t answer coverage questions or give insurance advice.