Property and contents
Ask how the building, furniture, equipment and guest-related damage are addressed. Check limits, valuation, deductibles and excluded causes.
Hosting a room, a second property or several short-term rentals? Bring the whole arrangement into view before comparing insurance: the building, bookings, guests, income and people who help you operate.

 A.M. Fredericks UnderwritingABEX o/b Affiliated Broker Exchange
 Allianz Global RisksAmbri AssuranceApril Canada Inc.April MarineArthur J. Gallagher & Co
 AVRO Insurance ManagersBeazley Canada LimitedBerkley Insurance CompanyBlueCross BlueShield
 Burns & Wilcox CanadaCAA InsuranceCAN - Continental Insurance
 Cansure Underwriting LtdCaradoc Townsend MutualChes Special Risk Inc.Chubb InsuranceChutter Underwriting Services
 Core Underwriting ServicesDefinityDesjardins Financial Security Investments Inc.
 Dominion of Canada/Travelers/Travelers EssentialEagle Underwriting Group Inc.Echelon
 Excess Underwriting Corp.Facility Association
 Forward InsuranceGlobal Aerospace Underwriting
 Great-West LifeGroupAssureGroupOne Insurance
 HDI Global Specialty SE
 IA Excellence Life Insurance
 INGLE International
 Intact Public Entities
 La CapitaleLiberty International CanadaLynx Insurance UnderwritersMarkel
 NorthbridgeOld Republic
 Optiom
 PAL Insurance Brokers Canada
 Premier Canada AssurancePremier MarinePremium Marine
 Revolution Advanced Underwriting
 SignalSignature Risks
 South Western GroupSovereign GeneralSpecial Risk InsuranceSports & Fitness InsuranceSSQ AssuranceStarr Technical RisksStrategic UnderwritingSummit Underwriting Group Inc.The Boiler Inspection and Indemnity Company (BI&I)
 The Totten Insurance GroupTrans Canada
 TravelersTrinity Underwriting
 Unique Risks
 Victor Insurance
From Insurance Genie
Explore recent policy purchases shared through our participating insurance professionals.
Recent policies will appear here when the Insurance Genie CRM feed is connected.
A short-term rental insurance discussion should describe the property as it is actually used, including activity beyond one booking platform.
Use the Airbnb and short-term rental insurance guide for the wider coverage comparison, or review landlord insurance when discussing other rental arrangements.
Avoid treating a platform benefit, property policy and liability policy as interchangeable. Ask the provider how the actual wording fits each exposure.
Ask how the building, furniture, equipment and guest-related damage are addressed. Check limits, valuation, deductibles and excluded causes.
Discuss allegations of injury or property damage involving guests and visitors. Confirm the insured activities, parties, limits and applicable exclusions.
Ask which event must occur before an income-related coverage responds, how the amount is determined and which waiting periods or limits apply.
Explain the role of property managers and service providers. Ask who needs their own insurance and which contract requirements should be reviewed.
Bring these questions to the provider before the next guest arrives.
Airbnb distinguishes Host damage protection from insurance. Read the platform terms and your own policy separately, then discuss gaps or overlaps with the licensed provider. See the Airbnb host damage protection guidance.
Describe the proposed rental use before relying on the existing policy. Ask the provider to confirm whether that activity can be covered and whether different terms or a different product are needed. Do not assume that a standard home policy automatically covers paid hosting.
Tell the provider about every channel, including direct bookings and other platforms. Ask which protection applies to each arrangement and how the wording treats periods between stays.
Use the same property, occupancy and business details across requests. Compare the insured activities, property values, liability limits, income wording, deductibles and annual cost. Ask the provider to explain any material differences.
Another host may have different property, occupancy, limits and claims information. A public example cannot determine your eligibility or final premium. Use an individual quote and review what it actually includes.
Be prepared
Hypothetical situations to help you prepare questions—not actual client claims or promises of coverage.
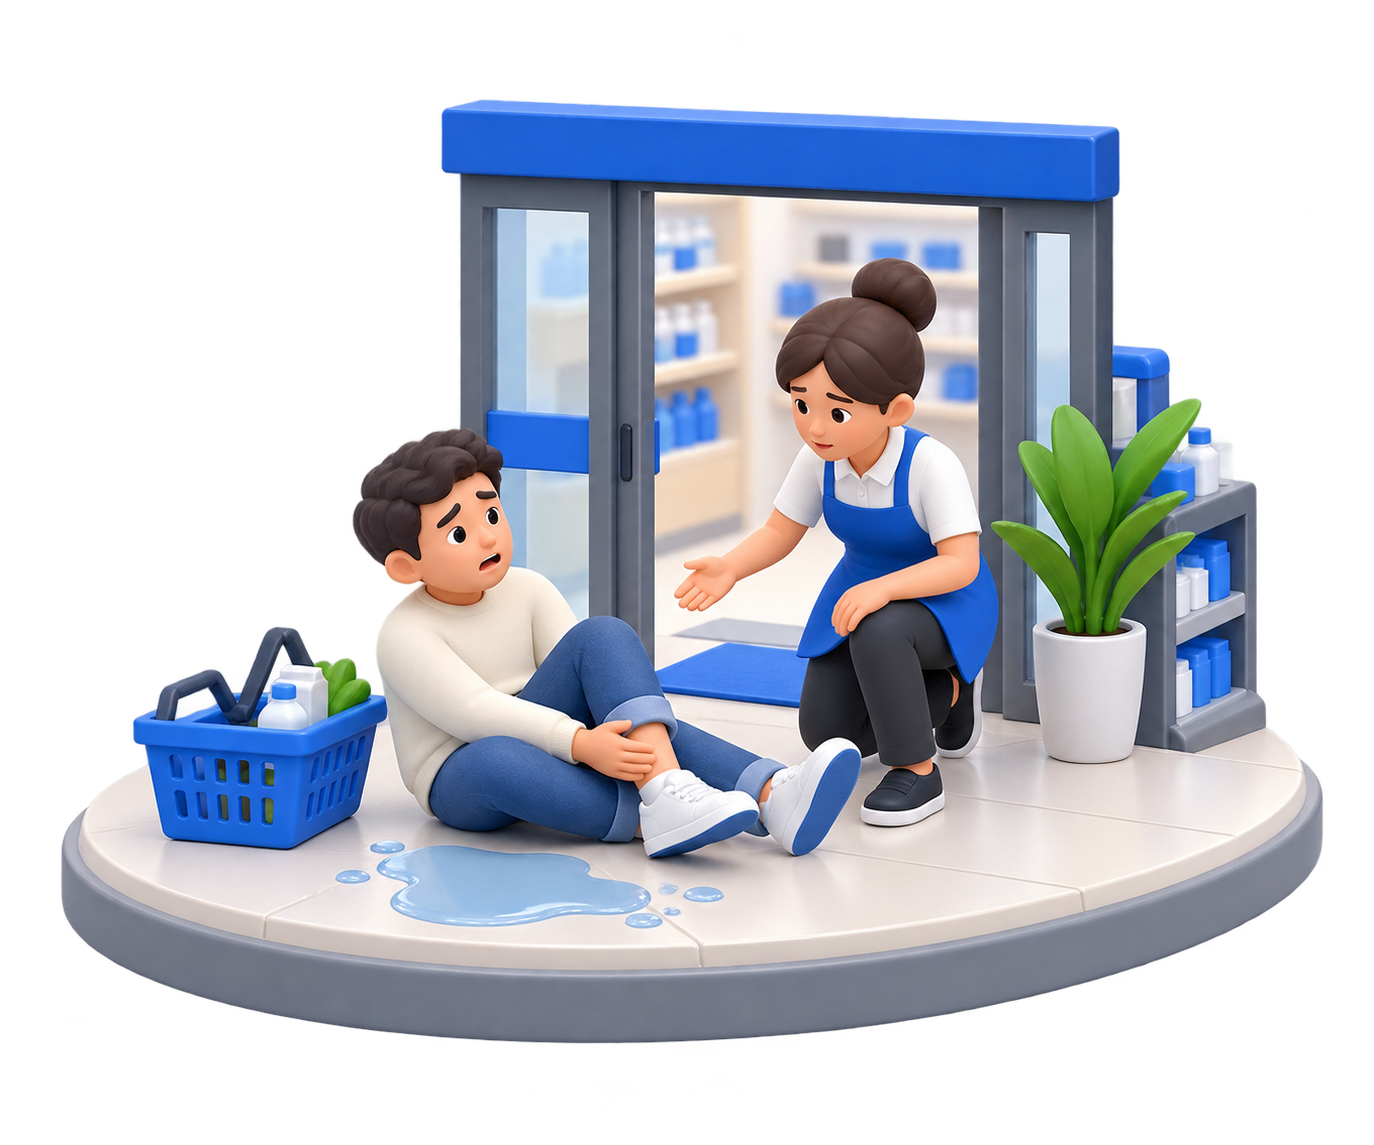
Scenario: Someone alleges an injury arose from the business operations.
What happens next: Preserve incident records and notify the insurer. Declared activities, liability wording and the facts determine whether a policy responds.
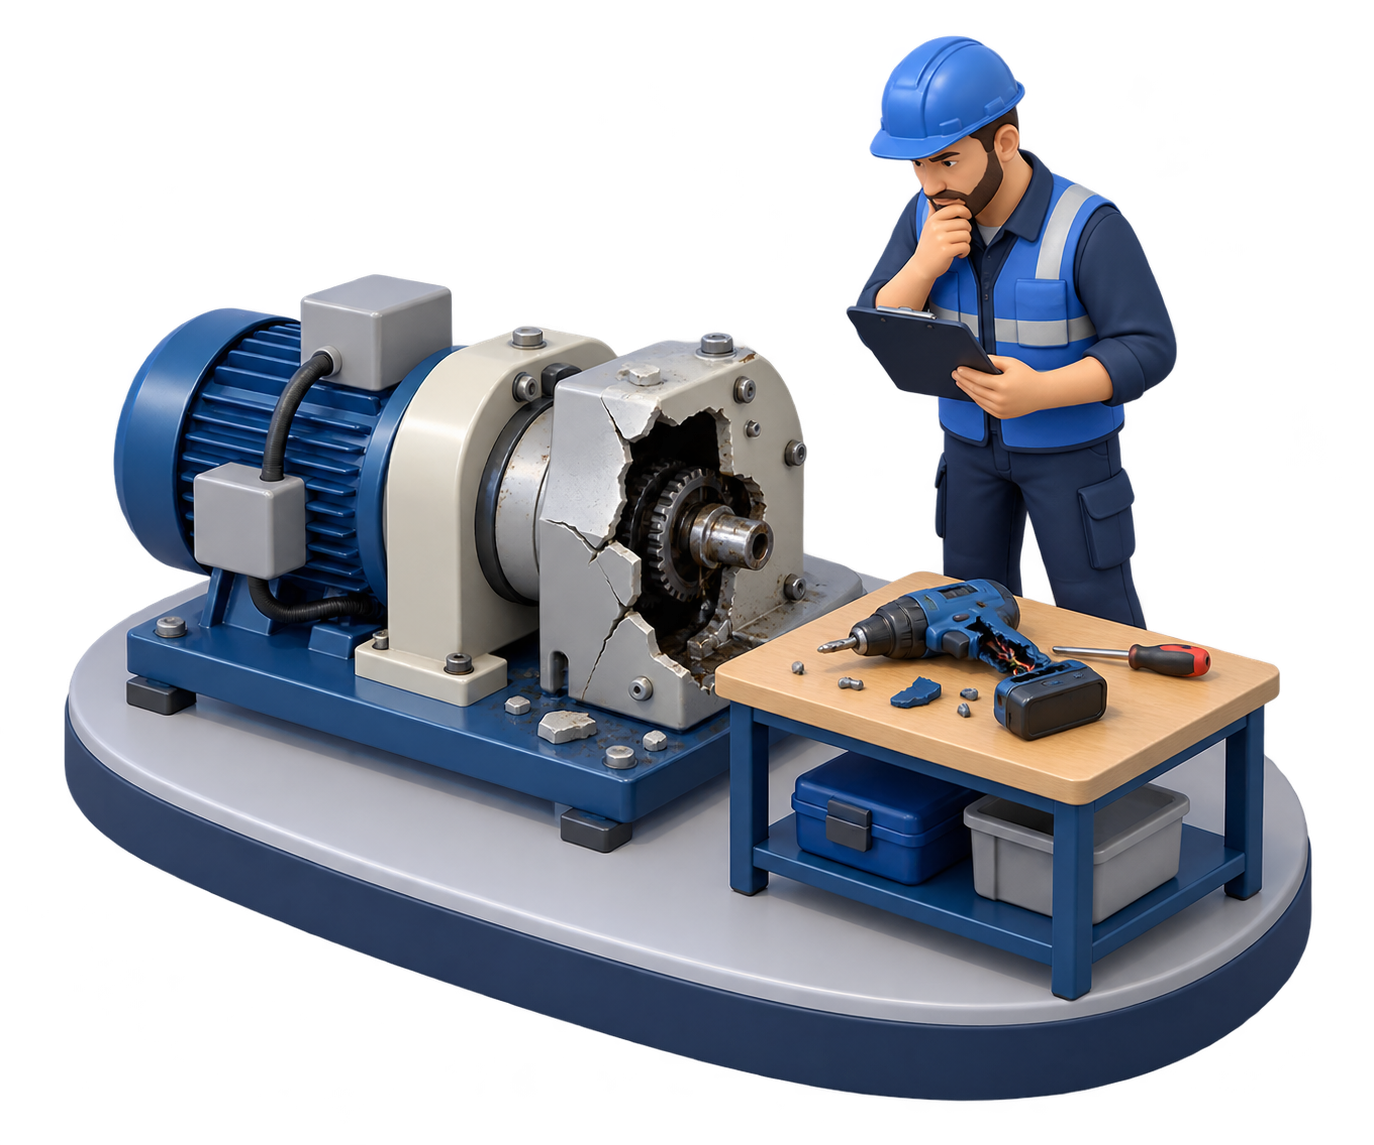
Scenario: Equipment used by the business is damaged or stolen.
What happens next: Document ownership, location and cause. Ask the insurer to review the insured property, exclusions, valuation and deductible.
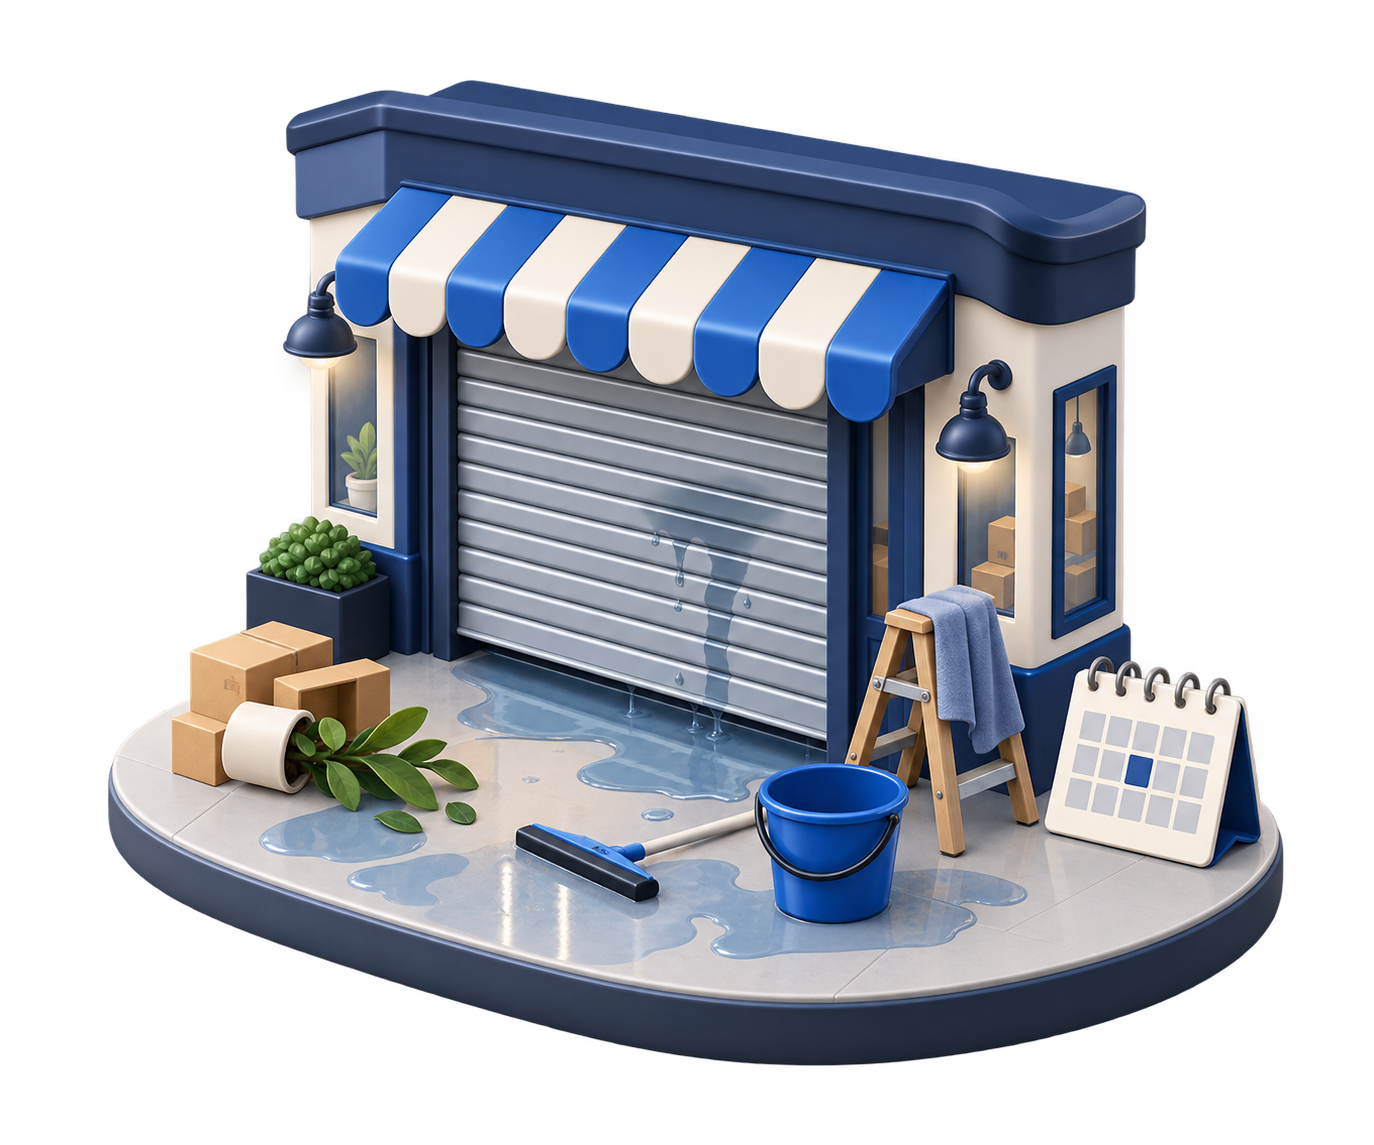
Scenario: Damage prevents the business from operating normally.
What happens next: Keep revenue and expense records. Business interruption depends on the insured trigger, selected coverage and applicable terms.
Actual outcomes depend on the facts and applicable wording. Read claims guidance · Ask about the next step
Hi, I’m Genie. I can explain how this website works, help you find a page, or point you to a person. I can’t answer coverage questions or give insurance advice.